
Quicken: Intelligent Money
- Rating
- 4.7
- Downloads
- 500.00K
- Content Rating
- Everyone
Quicken: Intelligent Money - Screenshots
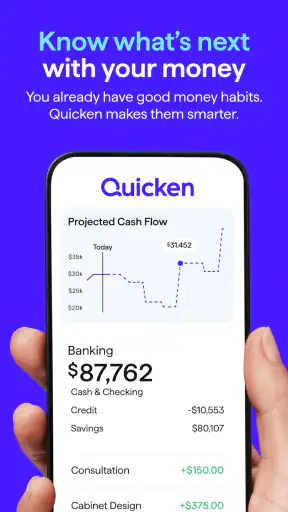
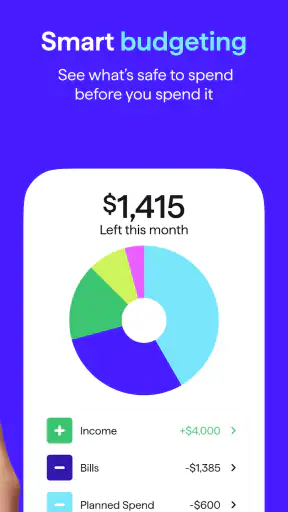
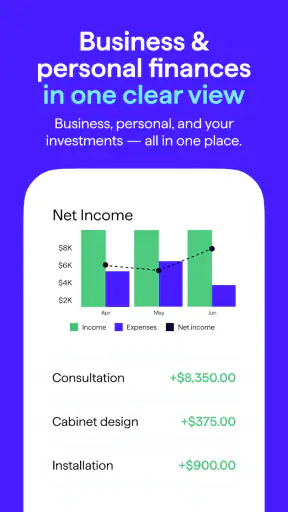
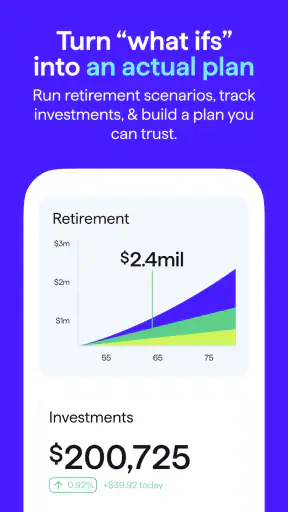
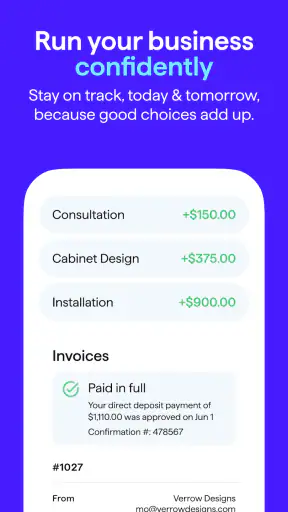
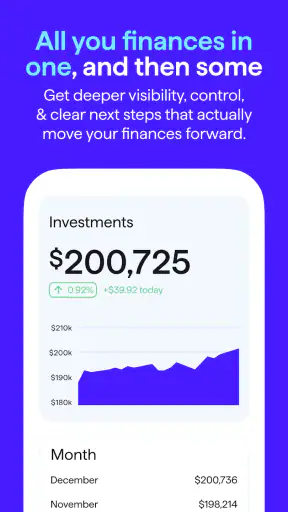
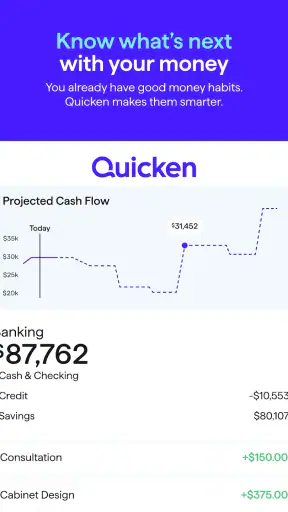
Pros
- Clear budgeting tools help track spending and organize finances.
- Automatic transaction categorization reduces manual data entry.
- Supports account aggregation for a broader view of your finances.
- Useful reports reveal spending patterns and financial trends.
- Bill tracking can help prevent missed payments and late fees.
Cons
- Many useful features require a paid subscription.
- Some financial institutions may not sync reliably.
- The interface can feel complex for first-time budgeting users.
- Investment tools may be limited compared with dedicated platforms.
- Personal finance data requires careful attention to privacy settings.
Quicken: Intelligent Money - Description
- App Name
- Quicken: Intelligent Money
- Package Name
- com.quicken.acme
- Developer
- Quicken Inc.
- Category
- Finance
- Last Updated
- Oct 1, 2019
- Version
- Varies with Device
I came away from Quicken: Intelligent Money seeing it as a serious personal-finance companion rather than a quick expense notebook. It is built for people who want to look across budgets, spending, and broader money decisions in one place, with the added angle of tools for small-business finances. That wider scope is useful, but it also means the app asks more from you than a very simple budgeting app.
The app is free to install, is listed for Everyone, and comes from Quicken Inc., a developer with a long association with personal-finance software. Its current store presence shows a 4.7 average from around 4.9 thousand ratings, with more than 500 thousand installs. Those figures suggest a well-established mobile product, although popularity alone does not guarantee that its approach will suit every household.
How Quicken: Intelligent Money feels in everyday use
My first impression is that the app makes more sense when I treat it as a regular money check-in rather than something I open only after overspending. A quick visit can help me see where the month is heading, while a longer session is better for reviewing categories, adjusting plans, or separating personal decisions from small-business activity.
That distinction matters. Many basic finance apps are designed around one question: “Where did my money go?” Quicken aims at a broader question: “What is happening across my financial life, and what should I do next?” The second question is more useful for planning, but it can also feel heavier if all I want is a quick list of recent purchases.
The budgeting side is the natural starting point. I would use it to give recurring spending a place, identify categories that regularly run high, and compare intentions with actual habits. The value is not in entering a perfect plan once. It comes from returning often enough to notice patterns before they become surprises.
For example, imagine I am paid near the end of the month and have several automatic bills arriving during the first week of the next one. A simple balance check might make me feel comfortable, while a budget view can expose the timing problem. I can then decide whether to reserve money earlier, reduce flexible spending, or move a planned purchase. That kind of calendar-aware thinking is where a dedicated finance app can be more helpful than a notes app or spreadsheet.
A better workflow for personal budgets
I would begin with a small number of useful categories instead of trying to classify every purchase with extreme precision. Housing, transport, food, subscriptions, debt payments, savings, and discretionary spending usually tell me more than dozens of tiny labels. Once the broad picture is reliable, more detailed categories can be added only where they support a real decision.
One practical habit is to review unusual transactions separately from normal monthly spending. A one-off repair, annual renewal, or holiday purchase can distort a category and make the following month look better or worse than it really is. I find it more useful to ask whether the expense is recurring, seasonal, or genuinely exceptional before changing the budget around it.
Another useful approach is to use the app as a conversation starter for household money. Instead of arguing about individual purchases, I can focus on a category that consistently needs attention. That shifts the discussion from blame to planning. It is a small change, but it makes budgeting more sustainable for couples or families who otherwise avoid financial reviews.
There is also a trade-off here: a detailed system only works if I keep it current. If I postpone reviews for too long, the app becomes a record of old information rather than a guide for the next decision. I would recommend a short weekly check and a deeper monthly review, especially during the first few weeks of use.
Where the small-business angle becomes useful
The inclusion of small-business tools gives this app a different purpose from many household budget trackers. A freelancer, contractor, or side-business owner may need to look at personal spending while also keeping an eye on business-related money. Having both concerns in the same financial workflow can reduce the need to switch between unrelated tools.
That does not mean I would automatically treat it as a complete replacement for professional bookkeeping. Small businesses can have obligations involving taxes, invoices, records, and formal reporting. The app is more appealing to someone who needs visibility and organization than to a growing company that requires a specialist accounting system with strict operational controls.
A sensible workflow would be to review business-related activity on a separate schedule from household spending. I might check personal cash flow each week, then review business income and expenses at the end of the month. Keeping those mental routines distinct helps prevent a profitable business month from hiding pressure in the household budget, or the other way around.
This is one of the less obvious strengths of the product: it can encourage better boundaries between money that feels available and money that has a specific job. For a person with irregular income, that distinction may be more valuable than a flashy spending chart.
What has changed, and what the current version means for users
The app was released on October 1, 2019, and its identity has developed around combining budgeting and personal-finance tracking with small-business tools. That evolution is important because it explains why the experience may feel broader than a purpose-built spending tracker. It is not simply trying to make a list of purchases look attractive; it is positioned as a more complete financial workspace.
The verified release history gives me a useful baseline, but I would separate that from assumptions about future updates. A product can expand its focus over time without every new idea becoming equally valuable in daily use. I would judge changes by whether they make reviews faster, improve clarity, or reduce the manual work involved in keeping finances organized.
For existing users, the broader direction can be positive if their needs have grown. Someone who began with household budgeting may later start freelance work, manage irregular income, or want a more structured view of business expenses. In that situation, staying within the same ecosystem may be more convenient than rebuilding years of habits elsewhere.
There is a possible downside for long-time users who prefer a minimal interface. As more financial tasks are brought together, the app can feel less immediate. New users may need time to understand which parts matter to them and which can be ignored. I would not try to configure everything on the first day. A gradual setup produces a cleaner and more useful result.
The app’s free entry point makes that gradual approach easier. I can explore the basic experience before deciding whether the broader offering is worth continued investment. At the same time, in-app purchases range from $9.99 to $109.99 per item, so I would check the purchase screen carefully and think about the long-term value before committing to anything beyond the free starting point.
That pricing range also changes how I compare it with alternatives. A free spreadsheet may cost nothing beyond my time, while a lightweight budget app may be simpler to understand. Quicken becomes more compelling when the convenience of a dedicated finance environment saves enough effort to justify its paid options. If I only track a few categories and rarely review them, a simpler alternative may be the better choice.
How it compares with spreadsheets and simpler trackers
A spreadsheet gives me maximum control. I can design any columns, formulas, and views I want, and I can keep the system as simple or complex as my skills allow. Its weakness is maintenance: I have to build the structure, protect it from mistakes, and decide how to interpret the information. Quicken offers a more guided path for people who want financial organization without designing the whole system themselves.
A basic expense tracker is usually faster for recording a purchase. It may be the right choice for someone who wants a private daily log and nothing more. Quicken is better suited to someone who wants those entries to support budgets, longer-term reviews, and a more connected view of personal and business money. The extra scope is useful only if I actually use it.
Traditional desktop-oriented finance software can offer depth, but mobile access changes the moment when I can review money. A phone-based finance app is available while I am shopping, checking a bill, or deciding whether an unplanned purchase fits the month. That immediacy can make a budget more practical, provided I do not mistake instant access for automatic financial discipline.
For people who already have a trusted accounting workflow, Quicken may be unnecessary or even distracting. I would choose it for visibility and planning, not because every financial situation needs another layer of software. The best fit is someone who wants more structure than a notes app but less specialized complexity than a full business accounting setup.
Where the experience still needs patience
The main friction is conceptual rather than cosmetic: the app covers several money jobs, and those jobs do not all have the same rhythm. Budgeting is frequent, personal-finance review may be weekly or monthly, and small-business organization can follow an entirely different schedule. I need to decide what I am using it for before the interface becomes genuinely helpful.
There is also the human problem of incomplete information. No finance tool can rescue a budget that I do not review, categories that I never correct, or business and personal expenses that I treat casually. The app can organize my decisions, but it cannot make those decisions for me. I would rather have a modest, accurate setup than an ambitious one that I abandon after a few days.
Users who dislike financial administration should think carefully before choosing it. The wider feature set may look attractive, but it can create more responsibilities: checking classifications, reviewing plans, and deciding which figures deserve attention. Someone who wants a completely hands-off experience may be happier with a simpler banking view or a very lightweight tracker.
Privacy and account comfort are also personal considerations whenever I use a finance app. I would read the current permissions, account connection details, and purchase terms before relying on it for important financial decisions. Those checks are not unique to this product, but they are especially sensible when an app becomes part of a regular money routine.
Who should use it, and who should skip it
I would recommend Quicken to a household that wants a central place for budgets and broader financial reviews, especially if one person also earns money through freelance or small-business work. It is also a good candidate for someone who has outgrown a simple spending diary and wants a more deliberate monthly process.
I would be more cautious for a student or casual user who only needs to record daily purchases. The app may offer more scope than necessary, and the effort of maintaining a broader system could outweigh the benefit. A simple tracker or spreadsheet may provide a cleaner experience for that situation.
It may also be the wrong choice for a business that needs formal accounting operations rather than personal oversight. In that case, I would look for software designed specifically around the company’s reporting and compliance requirements, while using Quicken only if its personal-finance side still fills a separate need.
The Everyone age rating makes it approachable for a broad audience, but financial maturity matters more than the label. I would want a new user to understand that budgets are estimates, categories can be corrected, and an app view should support—not replace—careful judgment.
What I would watch before making it a long-term tool
If I were deciding whether to keep using the app, I would watch how quickly it turns routine reviews into useful decisions. Can I identify an upcoming pressure point without digging through several screens? Can I tell whether a high-spending month is a temporary event or a new pattern? Can I keep business activity mentally separate from household money? Those questions matter more to me than the number of available screens.
I would also pay attention to the balance between new capabilities and everyday simplicity. Product evolution is worthwhile when it removes friction or makes financial information easier to understand. It is less helpful when additional scope makes the basic budget harder to maintain. For existing users, the best changes will be the ones that preserve familiar routines while making deeper reviews more practical.
My advice is to test the app with one realistic goal for a full budgeting cycle. I might choose to understand subscription spending, prepare for irregular income, or separate freelance expenses from household costs. After that period, I would ask whether the app helped me make a decision I would otherwise have missed. That is a more honest test than judging it after a few minutes of setup.
Overall, Quicken: Intelligent Money is a capable choice for people who want their budget to connect with a wider view of personal and small-business finances. I like its potential for structured reviews and its usefulness in situations where simple balance checking is not enough. I would not recommend it automatically to everyone, because its wider purpose brings extra setup and ongoing attention.
For me, the deciding factor is willingness to participate. If I am prepared to review categories, plan around irregular expenses, and keep personal and business money conceptually organized, the app can become a valuable financial routine. If I want only a fast spending list with almost no maintenance, I would choose something simpler. The strongest reason to try it is not the size of its feature set, but whether that broader view helps you make calmer, better-timed money decisions.
FAQ
What is Quicken: Intelligent Money, and who is it designed for?
Quicken: Intelligent Money is a personal finance app designed to help users organize accounts, monitor spending, create budgets, track bills, and understand their overall financial position in one place. It is mainly aimed at individuals and households who want more structure than a basic banking app provides. It can be useful for beginners, although users with complex investments or business finances should review the available features carefully before subscribing.
Can Quicken: Intelligent Money connect to my bank and credit card accounts?
The app is intended to connect with supported financial institutions so transactions, balances, and account activity can be viewed together. However, compatibility may vary depending on your bank, country, account type, and the connection method used. Before downloading or paying for a plan, check whether your institutions are supported. You should also expect occasional connection errors, duplicate transactions, or delays that may require refreshing or manually correcting data.
Does Quicken: Intelligent Money automatically create budgets and categorize expenses?
Quicken can help organize spending by assigning transactions to categories and providing budgeting tools, reports, and financial summaries. Automatic categorization is convenient, but it is not always perfect: transfers, subscriptions, cash withdrawals, refunds, and unusual purchases may be placed in the wrong category. For reliable budgeting, review categories regularly and make corrections rather than assuming every transaction has been classified accurately.
Is Quicken: Intelligent Money free to use, or does it require a subscription?
Quicken: Intelligent Money is generally associated with subscription-based access rather than being a completely free finance tracker. The exact price, included tools, trial availability, and renewal terms can depend on the product version, platform, region, and current promotion. Check the official store listing or Quicken’s website before subscribing. Pay particular attention to automatic renewal, cancellation deadlines, and which premium features are included.
How secure is Quicken: Intelligent Money, and should I be concerned about linking financial accounts?
Because the app handles sensitive financial information, security should be considered before connecting accounts. Quicken uses account-protection measures and typically relies on secure connections or authorized data providers, but no online service is entirely risk-free. Use a strong, unique password, enable available security features, keep the app updated, and avoid accessing it on unsecured public networks. Download only from an official store and review privacy permissions before setup.


